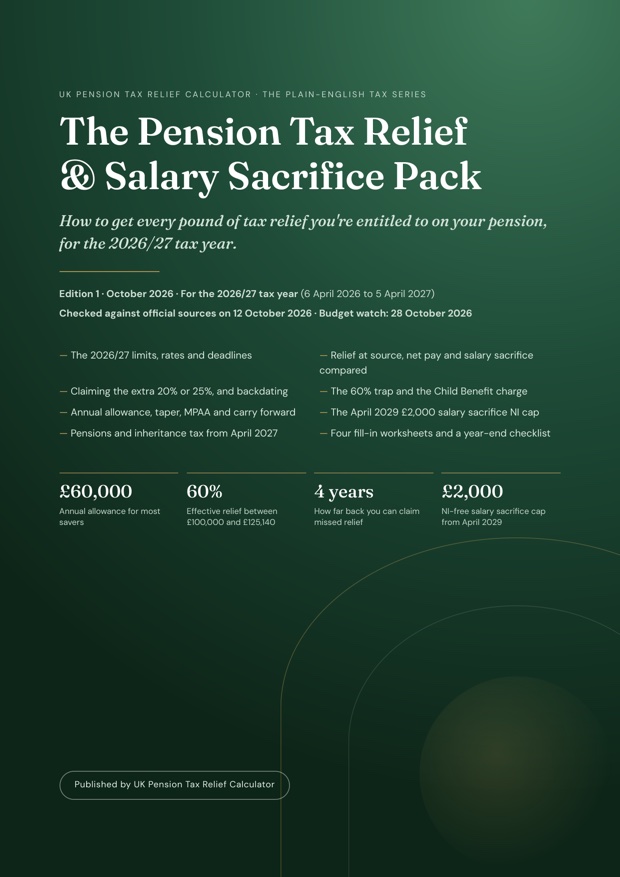
Edition 1 · October 2026 · 2026/27 tax year
Get every pound of pension tax relief you're entitled to
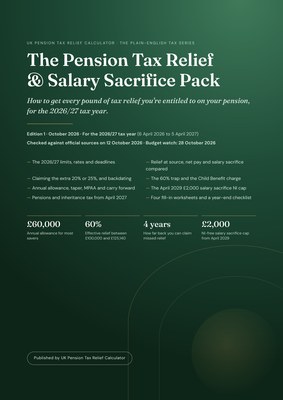
A 30-page plain-English PDF for 2026/27: how relief at source, net pay and salary sacrifice really compare, how higher and additional-rate taxpayers claim the extra 20% or 25% (and backdate it), the 60% trap, the annual allowance, taper and carry forward, and the April 2029 salary sacrifice NI cap.
- £60,000 annual allowance
- 60% relief between £100k and £125,140
- Backdate missed relief 4 years
- 4 fill-in worksheets
£4.99one-off · PDF, 30 pages
Instant download · no subscription · no account needed
- Secure payment by Stripe
- Download link valid 30 days
- Updated for 2026/27
Not what you needed? Contact us and we’ll refund you in full.
Checked against official sources (GOV.UK, HMRC manuals and legislation) on 12 October 2026.
Relief, allowances and salary sacrifice, explained with numbers
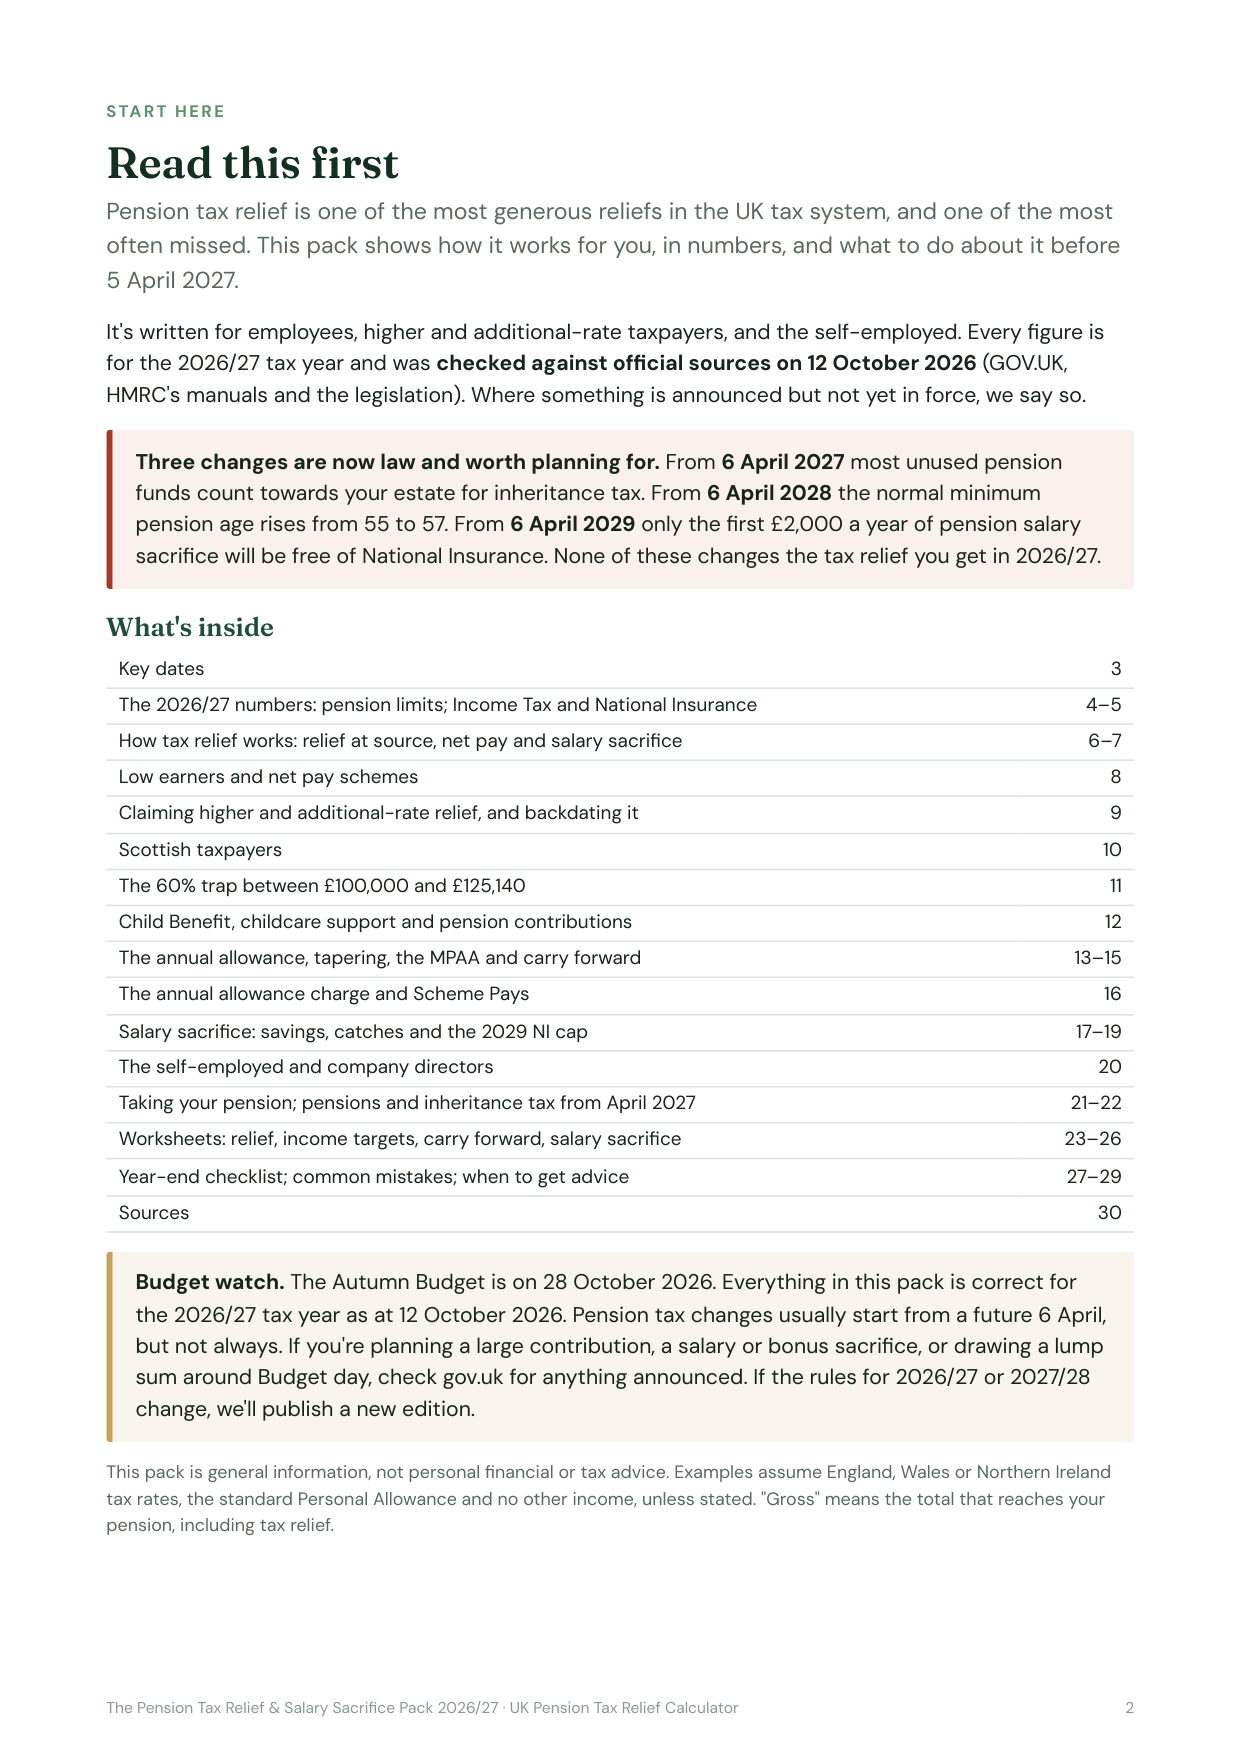
Three changes are now law and worth planning for: unused pension funds come into inheritance tax from 6 April 2027, the minimum pension age rises to 57 from 6 April 2028, and from 6 April 2029 only the first £2,000 a year of salary sacrifice is free of National Insurance. None of them changes the relief you get in 2026/27, so this year's numbers still count.
Three ways relief reaches your pension
Relief at source, net pay and salary sacrifice, with the same contribution worked through all three, plus the low-earner net pay gap.
Claiming the extra 20% or 25%
Higher and additional-rate taxpayers on relief at source must claim the rest themselves. How to claim, and how to backdate up to four years.
The 60% trap and Child Benefit
How contributions restore your Personal Allowance between £100,000 and £125,140, and cut the High Income Child Benefit Charge.
How much you can pay in
The £60,000 annual allowance, the tapered allowance, the MPAA, carry forward with a worked example, and the annual allowance charge and Scheme Pays.
Salary sacrifice: savings and catches
What it saves, the catches (minimum wage, statutory pay, mortgages) and what the April 2029 £2,000 NI cap means for you.
Worksheets and checklist
Fill-in worksheets for your relief claim, income targets, carry forward and a salary sacrifice comparison, plus a year-end checklist.
See the full contents page
- Read this first2
- Key dates3
- 2026/27: pension limits; Income Tax and National Insurance4–5
- How tax relief works: relief at source, net pay and salary sacrifice6–7
- Low earners and net pay schemes8
- Claiming higher and additional-rate relief, and backdating it9
- Scottish taxpayers10
- The 60% trap between £100,000 and £125,14011
- Child Benefit, childcare support and pension contributions12
- The annual allowance, tapering, the MPAA and carry forward13–15
- The annual allowance charge and Scheme Pays16
- Salary sacrifice: savings, catches and the 2029 NI cap17–19
- The self-employed and company directors20
- Taking your pension; pensions and inheritance tax from April 202721–22
- Worksheets: relief, income targets, carry forward, salary sacrifice23–26
- Year-end checklist; common mistakes; when to get advice27–29
- Sources30
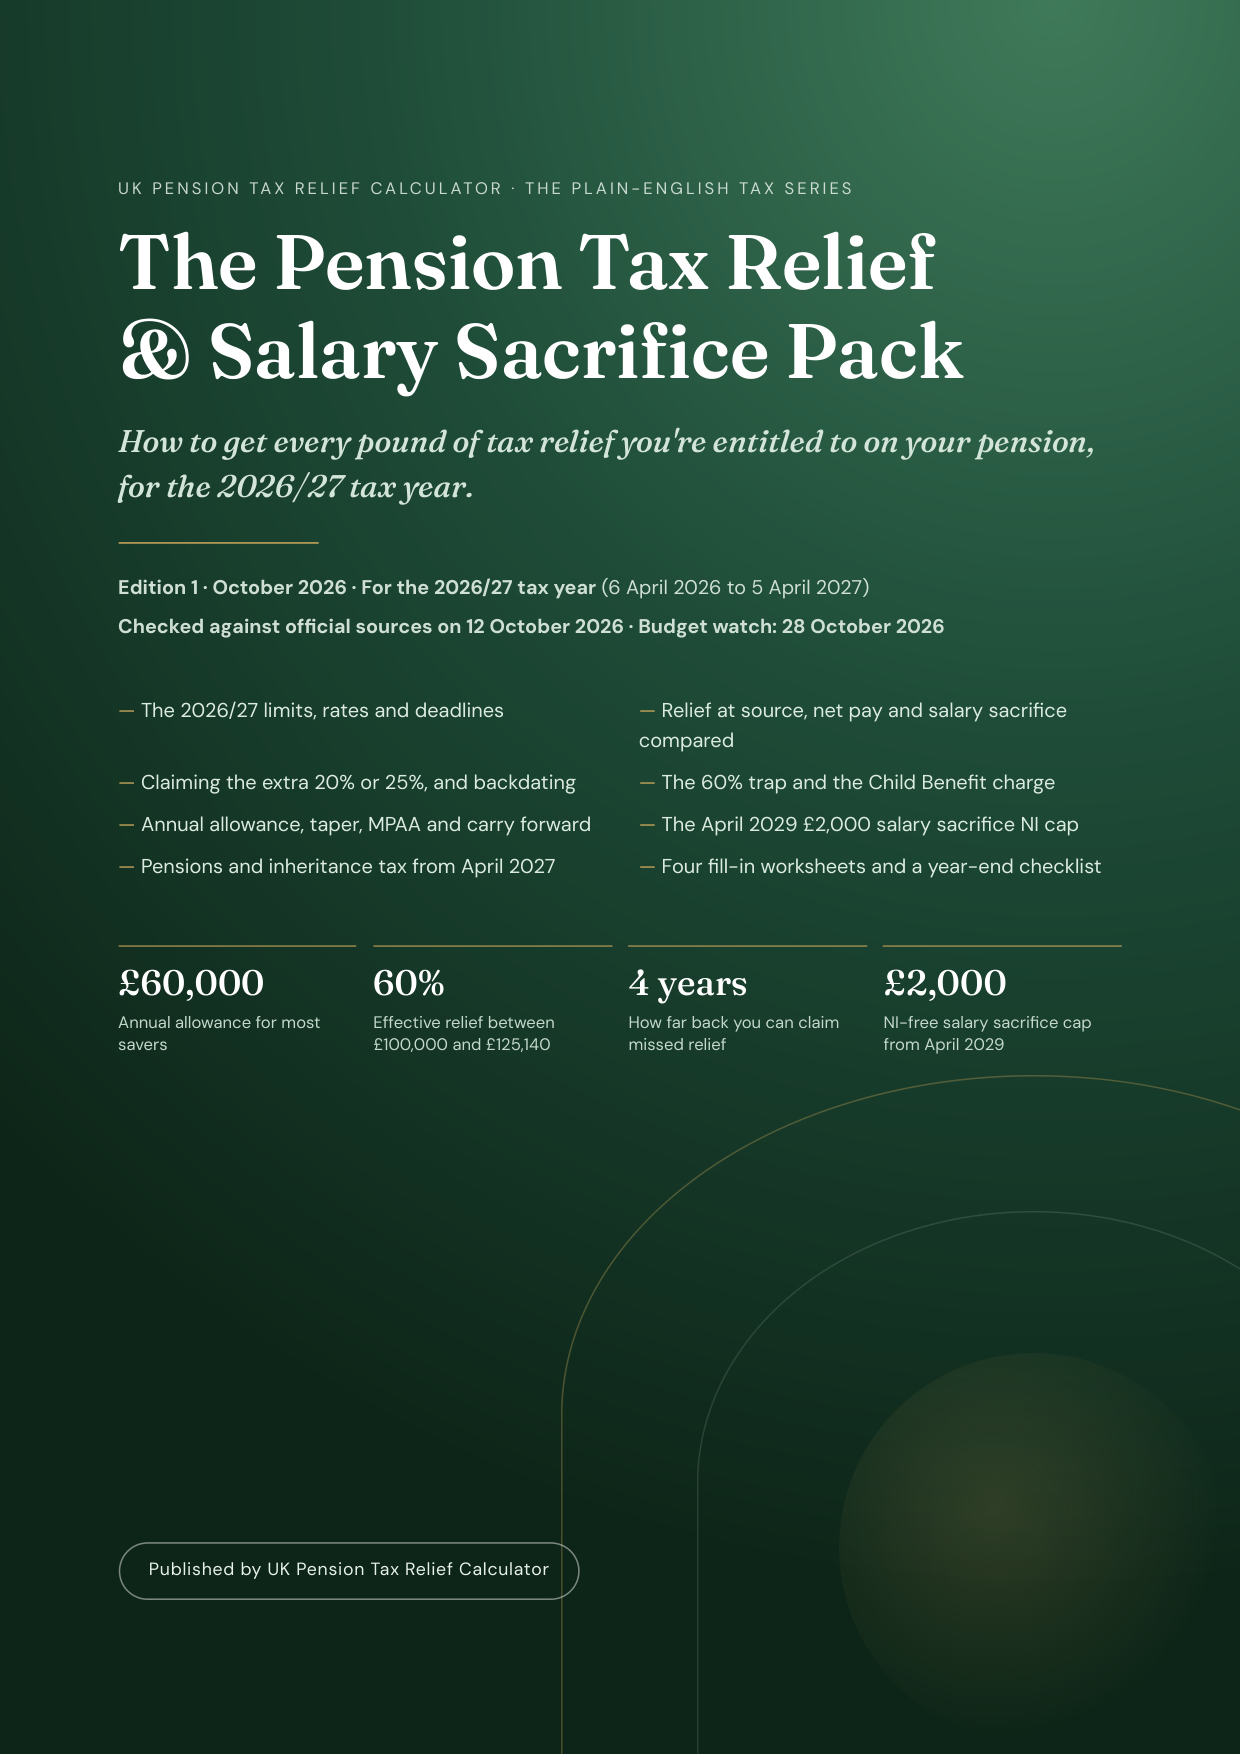
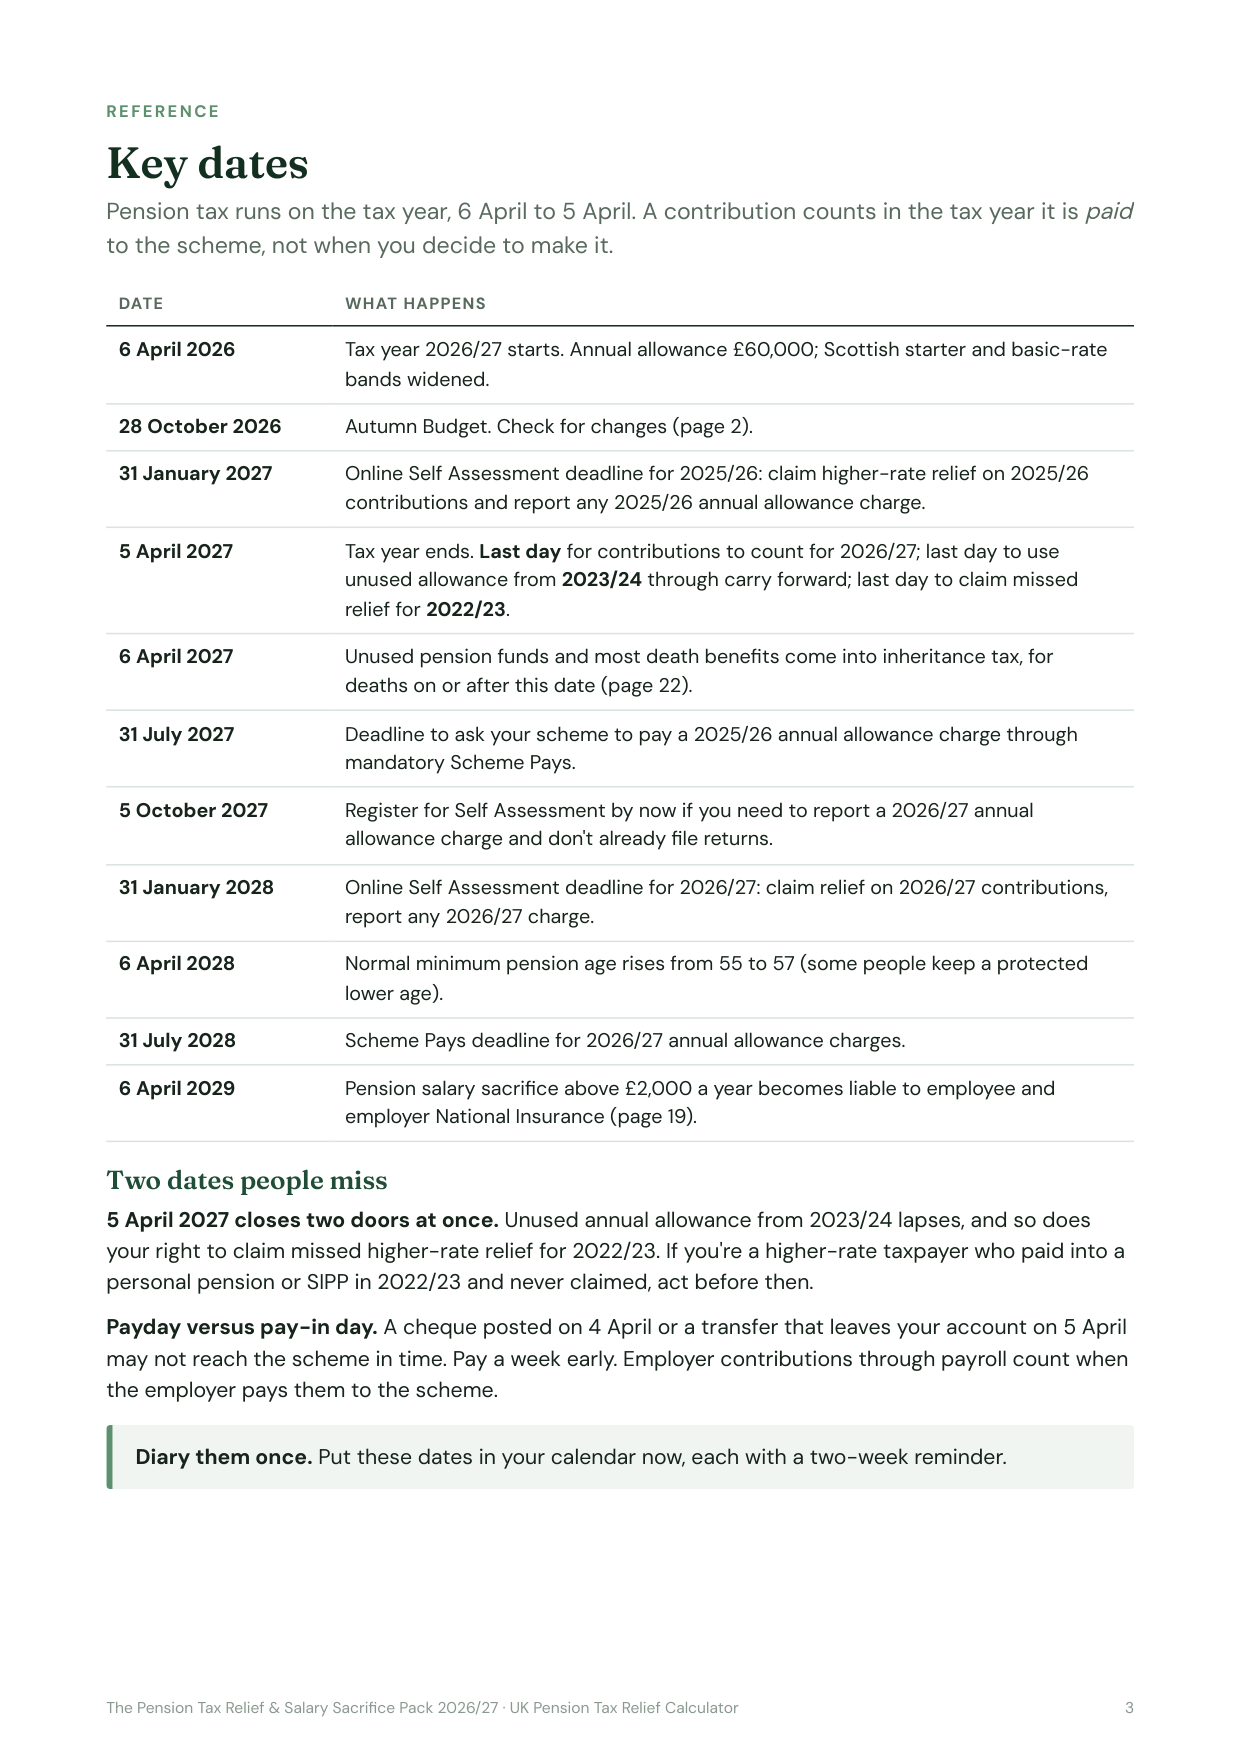
Three real pages from the pack
Tap a page to see it full size.
Written for savers who want the relief they're due
A good fit if you…
- pay 40% or 45% tax and pay into a personal pension or SIPP
- earn between £100,000 and £125,140, or get Child Benefit
- are deciding whether salary sacrifice is worth it for you
- are self-employed or a company director paying into a pension
Probably not for you if…
- you need regulated advice on investments or transfers: the pack is general information
- you're already drawing a defined benefit pension and not paying in
- your only question is the State Pension
Frequently asked questions
What exactly do I get?
A 30-page PDF, Edition 1 for the 2026/27 tax year (6 April 2026 to 5 April 2027). You download it straight after paying and can re-download it for 30 days.
Is it up to date for 2026/27?
Yes. Every figure was checked against GOV.UK, HMRC's manuals and the legislation on 12 October 2026. If the 28 October 2026 Budget changes the rules for 2026/27 or 2027/28, we'll publish a new edition.
Does it cover Scotland?
Yes. There's a page for Scottish taxpayers, whose relief works differently because of the Scottish income tax bands. Other examples use England, Wales and Northern Ireland rates.
Is this financial advice?
No. It's general information in plain English, with worked examples and worksheets. It includes a page on when it's worth getting regulated advice.
Can I get a refund?
Yes. If it isn't what you needed, use our contact page and we'll refund you in full.
5 April 2027 is the last day to use unused 2023/24 allowance and to claim missed relief for 2022/23. 30 pages, worked examples, four worksheets and a year-end checklist.
One-off £4.99 · instant PDF download · refunds via our contact page